


Watches of Switzerland (‘WOSG’) is a retailer and partner to Rolex and other watch brands.
It is one of the companies I write about most regularly behind a paywall at Hidden Gems Investing, and today I’m opening that up to free subscribers.
Most of the company’s value lies in its relationship with Rolex, which only sells through authorized retailers like WOSG. That makes WOSG’s economics far superior to a typical retailer and more like a subsidiary of Rolex.
Rolex is one of the world’s most iconic brands, and almost every Rolex is sold off a long customer waitlist. Prices only go up over time, and stores strictly adhere to Rolex’s recommended retail prices, which means no price competition and no inventory risk. There is no online competition either, as that would prevent customers from being vetted and having the ‘Rolex experience’ in a WOSG store.
My estimate is that WOSG’s store-level ROIC on Rolex sales is around 50%. I have spoken with 57 watch industry sources over the last couple of years, and many told me that being selected as a Rolex retailer is “like being given a license to print money”.
Importantly, WOSG is the number one partner to Rolex in both the US and UK, and it keeps gaining share as Rolex uses it to consolidate the market.
Management are competent, experienced, and well incentivized, with CEO Brian Duffy owning ~£70mm of stock and options. Duffy joined in 2014 and has grown WOSG’s share of Rolex sales in the UK from 35% to 50%. This encouraged Rolex to entrust WOSG with replicating its strategy in the US, where it is now the number one player with 10%+ share and has grown at 25% p.a. for the last five years.
Two years ago, I published a 30-page Special Report on WOSG, based on interviews with 19 industry sources and 10 store visits. While the stock has almost doubled since then, WOSG remains one of my largest positions today and I continue to believe it is greatly undervalued.
You can read my full Special Report at the link below, which I think still provides a good primer on the industry and company.

The stock today trades on 15x EV/FCF for a Rolex-like business with a long runway to grow organically at high single-digits and consolidate the market through M&A to bring total revenue growth to low/mid teens per annum. Management have also done a great job building out several businesses growing at ~25% that I think investors underappreciate.
The stock is a quality compounder that has traded well above 20x at times in the past, and I believe could do so again in future.
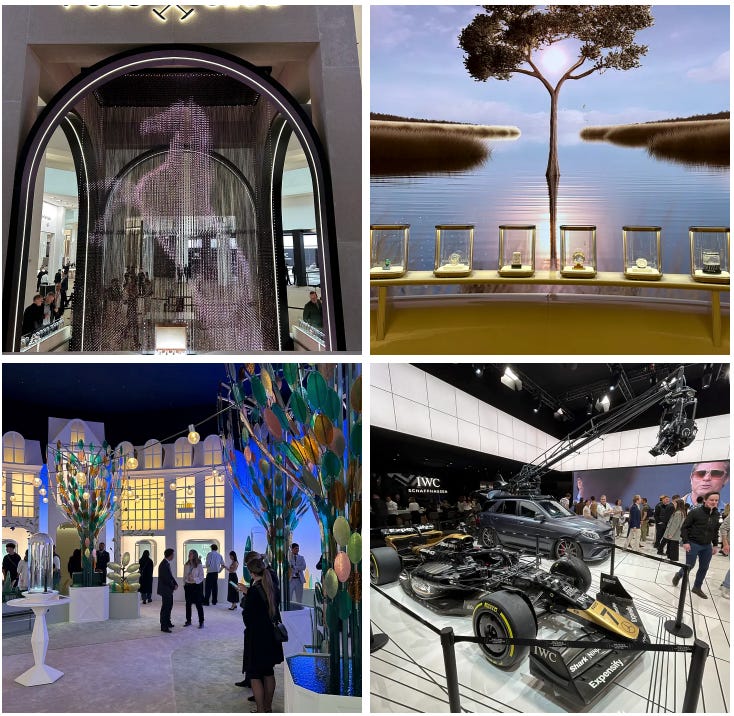
Since the report, I have had 38 more conversations with industry sources and visited the industry’s biggest trade show called Watches & Wonders in Switzerland.
You can read my full update from the trade show here:

Here is how I think about WOSG today, based on those conversations, analysis of 5,124 comments from customers who purchased a Rolex, and scrapping Rolex’s store count over the last two years.
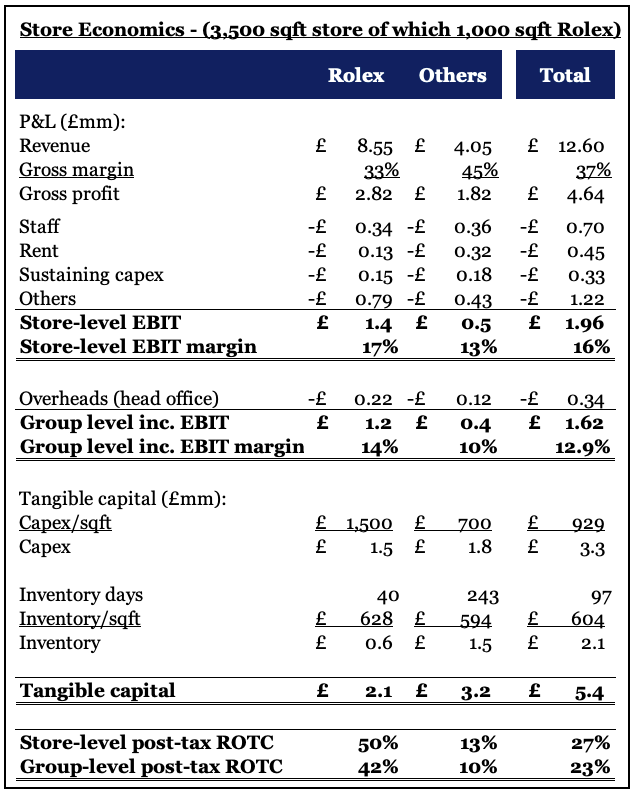
Many investors still underappreciate the quality of the Rolex business, because WOSG keeps secret the difference in economics between Rolex and other brands. However, my conversations and analysis suggests that in a hypothetical 3,500 sqft WOSG store generating £12.6mm in sales, Rolex takes 29% of the space but generates 68% of the revenues and 75% of the profits.
The difference in ROIC is even greater. Because Rolex watches are effectively pre-sold, the inventory turns extremely quickly and I estimate store-level ROICs are around 50% for Rolex vs 13% for the other brands.
WOSG was Rolex’s first retail partner and their relationship goes back to 1919, not long after Rolex’s founding in 1905. The company has grown its UK Rolex market share from 35% to 50% over the last decade.
WOSG’s competitive advantage is its scale.
Rolex increasingly only grants allocations to a few large partners like WOSG who can invest millions into each store to provide customers with an amazing ‘Rolex experience’. For context, when I wrote the Special Report in FY23 WOSG generated £890mm of revenues in the UK while the next three largest retailers generated a combined £220mm and spent £8mm in capex. The gap has grown since.
That £8mm of capex pales in comparison to WOSG, which is increasingly spending more than that on a single store as it builds flagship locations that I would liken to a ‘Disneyland of Rolex’, something which virtually none of its competitors can afford.
As an example, last year WOSG replaced its existing 900 sqft Rolex boutique on Bond Street in the West End of London with a three-story 8,000 sqft store dedicated entirely to Rolex. This is particularly significant because Rolex was founded in London, and having visited the store, and flagships in different countries, I believe it is probably the most impressive one in the world.

WOSG’s spending power is important because Rolex has been shrinking its retail network for decades even as it increases production, with the number of stores in the UK declining from 130 to 93 between 2014 to 2023. As the network continues to concentrate towards the stronger players WOSG will continue to gain share.
In fact, Rolex was so pleased with how WOSG developed the UK market that it encouraged the company to expand into the US and grow it in a similar way. WOSG has grown by 25% p.a. in the US in the last five years and the US is now half of company sales.
I have scraped data on all Rolex stores in the US for the last several years, and my analysis shows that while Rolex has shrunk the store base from 276 to 237, WOSG’s Rolex stores have grown from 19 to 24. You can see this in a dashboard I built: The table at the top shows how WOSG’s % share of the Rolex store base has grown, and the bottom table lists all of its competitors.
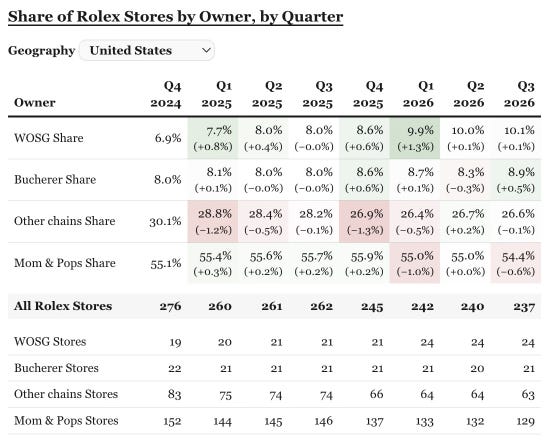
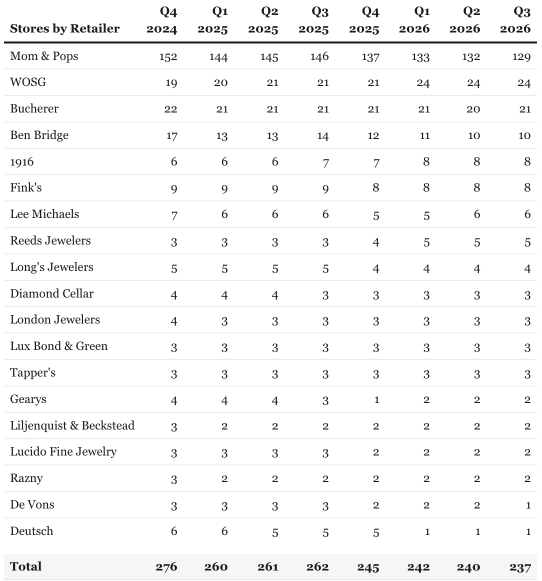
The result is that WOSG has increased its share of the store count from 6.9% to 10.1% in two years, and since its stores are typically larger than average its market share is well above 10%.
I think investors underappreciate that this is not only a path for large structural growth, but also provides a runway to make acquisitions at good returns.
In the table above you can see that most retailers have fewer than eight stores. As Rolex increasingly demands mom & pops invest millions in capex to upgrade their stores just to retain their allocations, many either do not have the ability or desire to invest that capital. Those become acquisition targets for WOSG, and there are many of them.
The other key point I think investors underappreciate is how resilient the Rolex and WOSG businesses are.
Many investors sold down the stock over the last year thinking that a slowdown in luxury spending, tariffs, and higher gold costs would cause WOSG to miss earnings. Instead, it beat full-year guidance.
The key reason is the length of Rolex’s waiting lists.
Neither Rolex nor WOSG tells us how long waiting lists are, but I have tracked and cleaned 5,124 comments online from real customers who purchased Rolex watches and stated how long they had to wait. As an example, the chart below shows that for two of Rolex’s key models, the Submariner and GMT-Master, US wait times are well above pre-Covid levels and contrary to popular belief have been strengthening since they bottomed in 2024.
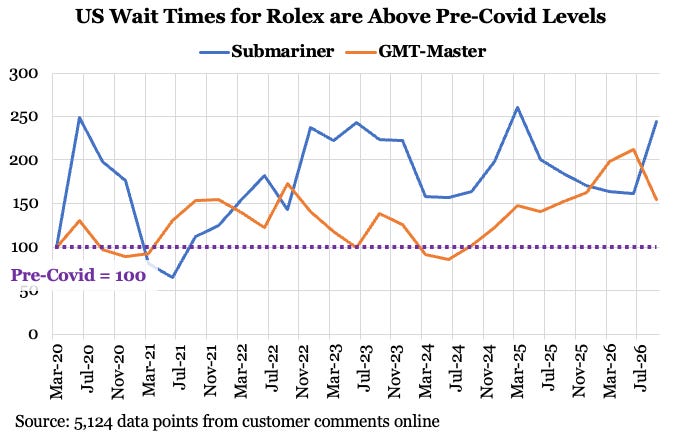
The length of the waitlist means WOSG is a very resilient business and has a buffer to macro shocks because even with a reduction in the waitlist they still sell every Rolex, as long as the waitlist does not reduce completely to zero.
Overall, despite the stock doubling since I published the Special Report, it continues to trade for 15x FCF for a business with a very long runway for 10%+ growth, tied to Rolex, a strong balance sheet, and demonstrated resilience over the last year. I continue to see a ~20% IRR from here.
I hope you enjoyed this look behind the paywall at Hidden Gems Investing. I look for ‘hidden gems’ in the small-cap value space that are usually leaders in niches. The defining feature of my research is that I do extensive primary research, typically sourcing and speaking with 20 industry experts prior to making an investment, with ongoing conversations and attendance at industry events like trade shows.
Join the 300+ subscribers who have upgraded to paid:
Still not convinced? Go here to learn more, and make sure you read the now-free Special Report on Watches of Switzerland for more background. I update subscribers on a regular basis, and you may also be interested in recent articles on WOSG’s Investor Day, growth runway, and valuation.
This article is for informational purposes only and is not investment advice. Plural Investing, LLC currently holds a position in Watches of Switzerland. Read important disclosures here.