


Watches & Wonders is the watch industry’s key trade show. Held in Geneva, Switzerland, the event brings together nearly all the major brands and 55,000 visitors.
Shortly before I arrived, President Trump announced tariffs of 31% on Switzerland. Many brands told me that although the news was a shock and responses have not been finalized, price rises are inevitable.
My biggest insights from the event are:
A 31% tariff reduces Watches of Switzerland group (“WOSG”) profits by around 15%.
Roughly speaking, an X% tariff reduces WOSG group profits by 0.5* X%. For instance, if tariffs come down to 15% then WOSG profits reduce by around 7.5%.
Rolex is not favoring Bucherer over other retailers in any material way and does not appear to have plans to.
I believe that WOSG’s stock price has overreacted to the news on tariffs. The company trades on 9x FCF for a business that should grow at low double digit rates in most years. I believe intrinsic value three years from now will likely be well over double today’s stock price.

Watches of Switzerland group (WOSG) is a retailer and partner to Rolex and other luxury watch brands. Most of the company’s value lies in its relationship with Rolex, which only sells through authorized retailers like WOSG. That makes WOSG’s economics far superior to a typical retailer and more like a subsidiary of Rolex.
Management are competent, experienced, and well incentivized, with CEO Brian Duffy owning £25mm of stock. Duffy joined in 2014 and his strategy of investing to elevate customer experiences has grown WOSG’s share of Rolex sales in the UK from around 35% to 50%. This encouraged Rolex to entrust WOSG with replicating its strategy in the US, where it is now the number one player with 10% share and has grown at 30% p.a. for the last five years.
The stock has fallen 75% since 2022 after Rolex acquired another retailer called Bucherer and the luxury watch bubble burst. Investors are concerned that WOSG’s relationship with Rolex is in danger, but our work suggests it is not and that even with tariffs the US offers a large structural opportunity for WOSG to deploy capital at 20% returns.
Subscribe now to read our 35 page Special Report based on conversations with 19 sources and 10 store visits.


Many brands had extraordinary boutiques at Watches & Wonders and did an impressive job of telling their stories, but one brand stood out far ahead of the others.
Rolex.
The trade show opened at 8.30am each day and I estimate that by 9am the Rolex boutique was surrounded by a long queue with a wait of around 30 minutes. By 10am the wait time had increased to an hour, while most boutiques still had little or no queue to enter.
In fact, the Rolex halo was so strong that even the boutique of it’s sister brand Tudor had a longer queue than any other brand.

Rolex’s boutique and exhibits themselves did not particularly stand out and were fairly limited. Almost all were focused on the new Land Dweller watches the company has released.
And while the watches are clearly impressive, I could not help but notice when touring the other boutiques that there are many other brands with watches that display a similar or even higher level of craftsmanship and technical excellence.
Why then is Rolex so dominant?
In the mind of many people Rolex is not just selling a watch, it is also selling prestige and status. I think a lot of that comes from the company’s continually brilliant marketing and partnerships over generations.
Rolex not only has the largest market share in the luxury watch market, it has an even larger share of mind.
And while some other brands can match the technical qualities of Rolex watches, that has not helped them gain market share because they have not gained share of mind.
From what I saw and heard, there is no brand that has a chance of closing the gap to Rolex in a material way. It would take decades of marketing and Rolex’s scale today allows it to invest much more in marketing than it’s competitors - meaning it’s moat is arguably widening.
This moat also resulted in a hierarchy to Watches & Wonders.
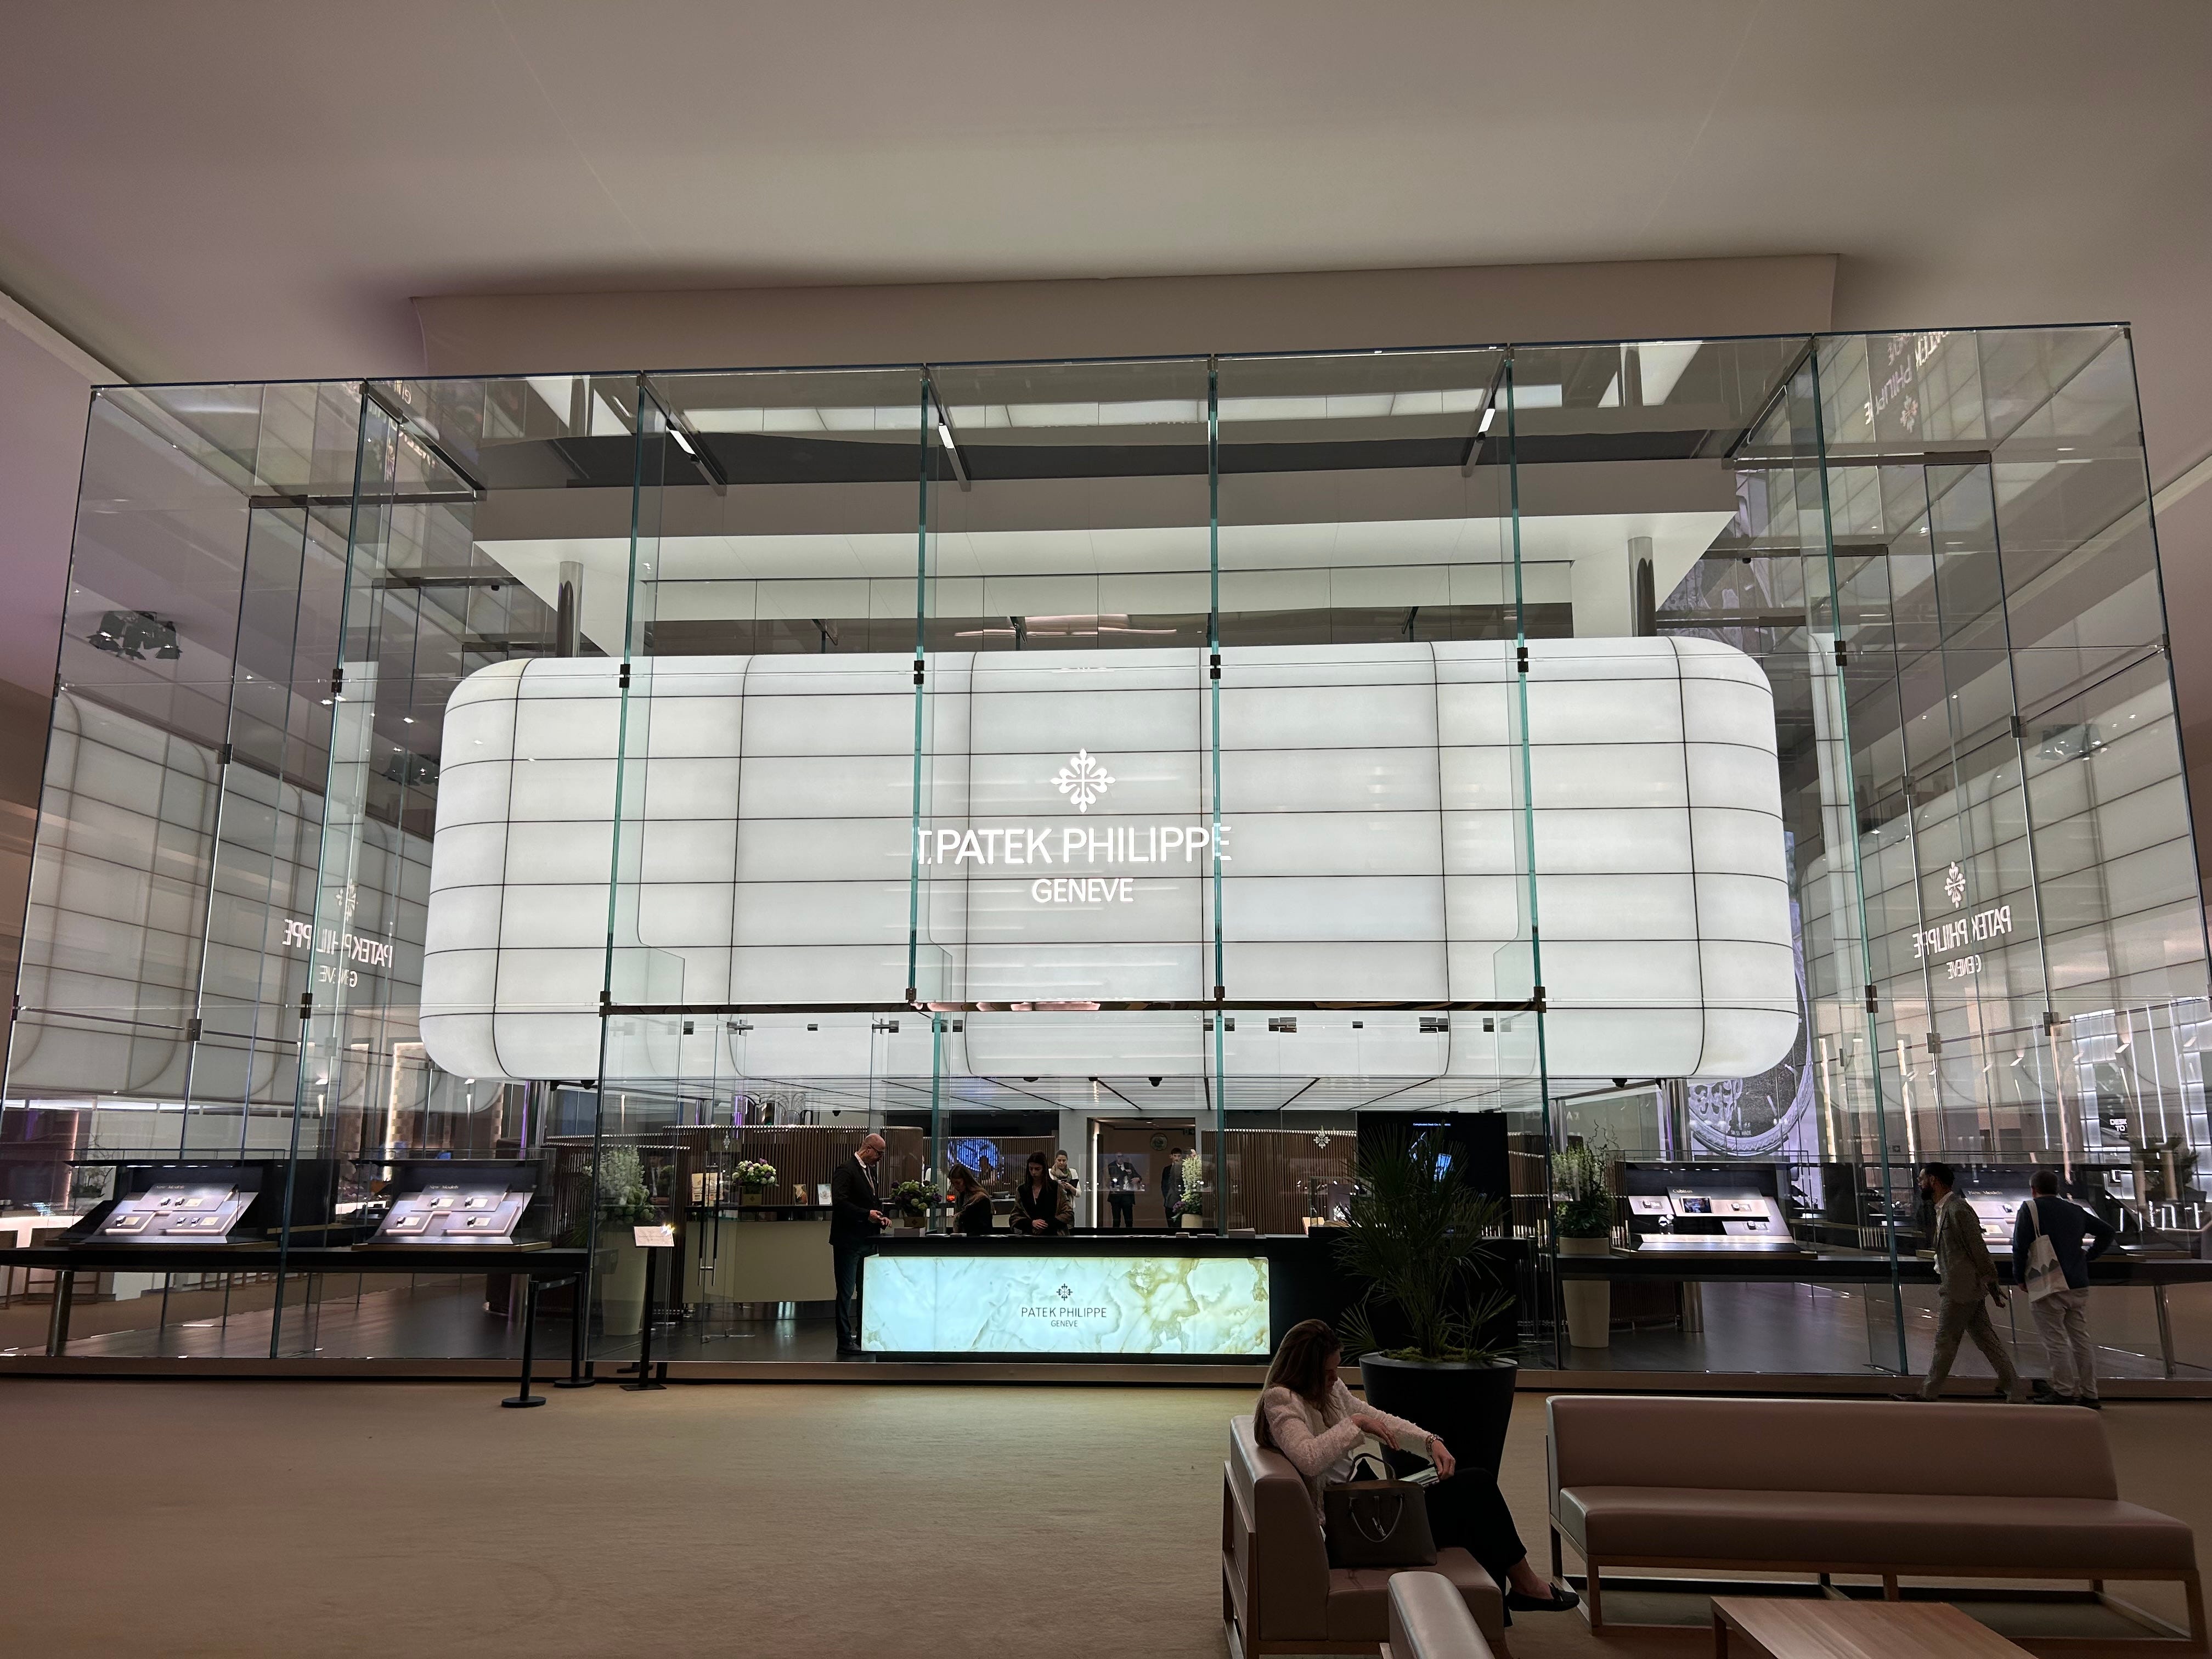
While Rolex’s boutique was the size of a building, most of this was reserved for VIPs and the public spaces were quite small. The allocation of space was reversed for most other brands. The only brand that felt more exclusive than Rolex was Patek Philippe, which had a boutique you could not even enter unless you were a VIP.
Tariff Impact on Watches of Switzerland
Nearly everyone from a non-waitlist brand told me that conditions were already difficult before the tariff news, although things were better in the US. Several non-waitlist brands even encouraged me to buy a watch on the spot.
Despite these conditions price rises sound inevitable, but no final decisions have been made as brands wait and see what the final tariff will be. Some brands had also moved more inventory into the US in anticipation of tariffs.
The head of pricing at one major brand told me they are waiting for an instruction from their parent company to co-ordinate price rises across all its brands.
Overall, my estimate is that a 31% tariff on Swiss imports reduces WOSG’s US earnings by about 31% and group earnings by about 15%. Intrinsic value should reduce by significantly less than 15% as tariffs may be reduced and/or temporary.
Here are models of the mechanics under different scenarios:
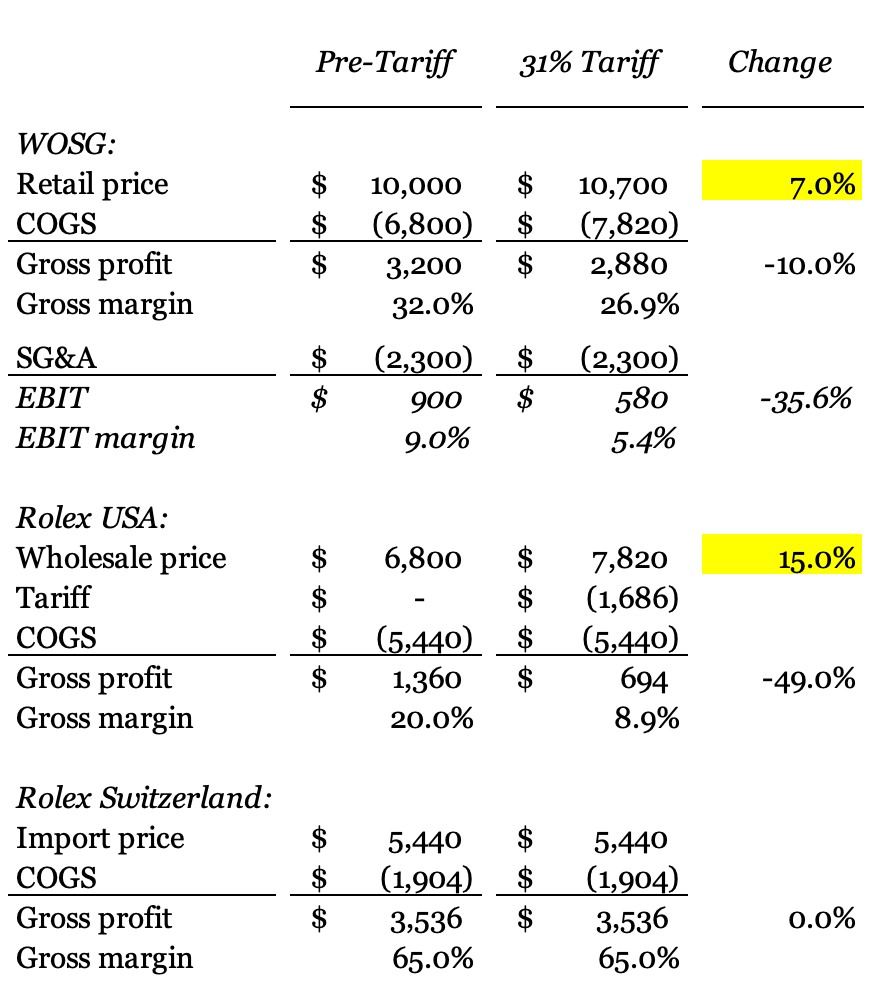
In the above example, suppose WOSG sells a Rolex for $10,000. WOSG buys that at a wholesale price of $6,800 from Rolex’s US subsidiary (“Rolex USA”).
Tariffs are not paid on the retail price of $10,000, but instead on the price of the import. In this example, Rolex USA imports the watch from Rolex Switzerland for $5,440.
The tariff is therefore 31% * $5,440 = $1,686. That’s 16.9% of retail prices, not 31%.
I’ve assumed that Rolex USA makes a 20% gross margin and Rolex Switzerland makes 65%, meaning Rolex books nearly all the profits after SG&A in Switzerland.
I don’t actually know what Rolex USA’s margin is, but Rolex’s UK subsidiary reported roughly 20% for 2023 and 2022 to Companies House, while the 65% for Rolex Switzerland is in line with other luxury businesses.
In the bearish scenario where 31% tariffs are permanent, my sense from discussions at Watches & Wonders is that Rolex will increase retail prices by around 7% and take back some margin from retailers by raising wholesale prices by 15%. Those price rises may take place over 12-18 months rather than all in one go.
That causes WOSG’s US gross profits to decline 10% and EBIT to decline by 36%. I would expect some reductions in SG&A and the US is half of WOSG’s earnings, so the net effect is likely to be around -30% in the US and -15% at the group level.
Rolex USA in this example takes a big 49% hit to gross profits, but since most of the profits are booked in Switzerland the combined US and Swiss gross profits are only down 14%.
There are two other offsetting factors that could mean the impact to Rolex is significantly less.
First, the Swiss franc is down 4% vs the US dollar since the tariff announcement, meaning Rolex’s input costs have reduced in US dollar terms.
Secondly, Rolex may raise prices globally by a small amount, like 2%, to reduce the opportunity for US consumers to travel and buy watches cheaper abroad. Since Rolex’s non-US sales are four times greater than US sales, a 2% price rise is equivalent to an additional 8% rise in the US.
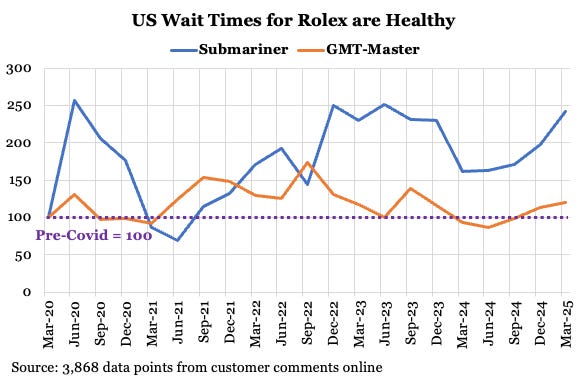
If Rolex raises global prices by 2% and input costs fall 4%, it’s global profits are actually unchanged in my model unless volumes decline. And since waitlists in the US remain healthy according to customer data, I expect that prices rises will result in a slightly reduced wait times but no change in the number of watches sold.
I also expect Rolex will tolerate at least some of the reduced profits from tariffs. Notably, a director at a similarly prestigious brand to Rolex told me he sees no reason to cut retailer margins.
For these reasons, I believe the 15% hit to WOSG’s group profits I’ve laid out above is relatively conservative.
In a scenario where tariffs on Switzerland are reduced to 15% instead of 31%, I estimate the hit to WOSG’s US profits is 15% and at a group level is around 7%. Achieving these economics would only require Rolex to raise retail prices by 4%.
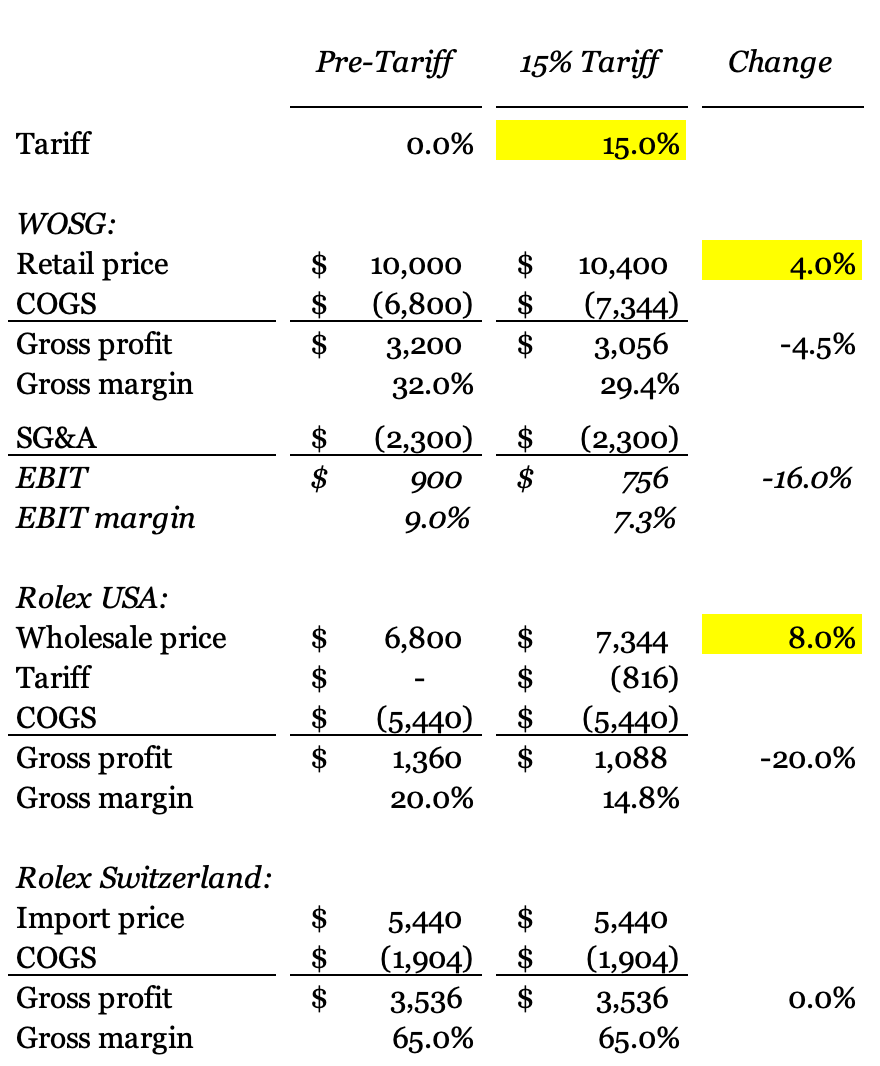
I believe some level of tariff reduction is likely. Switzerland has almost no tariffs on US products and appears very open to negotiating. I’ll let you decide what tariff outcome is most likely, but the simple rule of thumb is that an X% tariff reduces US profits by X% and group profits by 0.5 * X%.
Longer term, the bigger risk from tariffs in my view is whether there is a significant loss of wealth among US high net worth individuals. Although the global watch market has been struggling since the watch bubble burst in 2022, the US has continued to see healthy demand with financial assets around all-time highs and interest rates declining.
We have obviously seen a significant decline in stock markets and confidence since tariffs were announced, and there is a risk that higher inflation means interest rates do not come down. If that scenario plays out we could see a significant reduction in demand and wait lists.


Non-Waitlist Brands
Around 25% of WOSG’s sales are with non-waitlist brands like Omega, Cartier, TAG Heuer, and IWC. These brands are likely to be impacted significantly more than Rolex as they were already struggling with falling demand.
A price rise is inevitable but will be met with lower volumes, partly from US consumers buying watches abroad to avoid the price increase. That is easier for non-waitlist brands as consumers can simply walk into a store on vacation and buy a watch, rather than just register their interest and wait for a call in the future.
However, WOSG typically has nine months of inventory for these brands vs one month for Rolex, meaning there is a significant amount of time for tariffs to come down before profits are impacted.
The company also has more ability to push back against margin cuts from the non-waitlist brands as there are many more brands to choose from and not all brands are Swiss.
I therefore expect the overall reduction in WOSG’s profits will be similar to in the Rolex example, with the difference being the non-waitlist brands will bear a lot more of the impact than Rolex.
Rolex and Bucherer
I spoke with five people from Rolex, one from Tudor and two from Bucherer across the trade show and visits to the only entirely Rolex owned store in the world, which is in Geneva (Rolex owns Bucherer, but there is some separation between the operations).
Five of them said that Bucherer does not get any preferential treatment from Rolex despite the acquisition and that retailers are treated the same. Two of the people I spoke to did not have a strong opinion and one store attendant at Bucherer said they do get better treatment, although this appeared to be part of an attempt to sell me a watch.
While none of these were senior people, it is so rare to speak to anyone from Rolex that I thought it was worth asking the question. And I took it positively that no one from Rolex said Bucherer gets preferential treatment even when I pushed back or asked whether that will change in future.


If you enjoyed this article, click “like” or “share” to help it gain more visibility!
This article is for informational purposes only and is not investment advice. Plural Investing, LLC currently holds a position in Watches of Switzerland. Read important disclosures here.
Thank Chris for the report. Not exactly related to WOSG, but any idea which countries land you the best chance of securing a walk-in purchase? Asking as a Rolex enthusiast :)